

IT services provider Everforth (EFOR) announced better-than-expected revenue in Q3 2026, with revenue rising 2% year on year to $1.03 billion. On the other hand, next quarter’s revenue guidance of $980 million was less impressive, coming in 0.7% below analysts’ consensus estimates. Its non-GAAP profit of $1.11 per share was 6.6% above analysts’ consensus estimates.
For more on Everforth, read our free full research report.
Everforth (EFOR) Q3 2026 highlights:
- Revenue $1.03 billion vs S&P analysts’ consensus estimates of $1.01 billion (2% year-on-year growth, 2% beat)
- Adjusted EPS $1.11 vs S&P analysts’ consensus estimates of $1.04 (6.6% beat)
- Adjusted EBITDA $106.3 million vs analysts’ consensus estimates of $101.1 million (10.3% margin, 5.1% beat)
- Revenue guidance $980 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $987.2 million
- Adjusted EPS guidance $1.03 at the midpoint for Q4 2026, above analysts’ consensus estimates of $1.02
- EBITDA guidance $98 million at the midpoint for Q4 2026, in line with consensus estimates
- Operating margin 5.5%, down from 6.7% in the same quarter last year
- Free cash flow margin 4.5%, down from 7.1% in the same quarter last year
- Market capitalization $1.62 billion
“Everforth’s third quarter 2026 results demonstrated continued momentum in the business. Revenues of $1.03 billion and Adjusted EBITDA of $106.3 million surpassed the high end of our guidance, while Adjusted EBITDA margin of 10.3 percent was at the top end of our guidance range,” said Ted Hanson, Chief Executive Officer of Everforth, Inc. “As we enter the final quarter of the year, strong Commercial and Federal bookings reflect continued customer demand for AI and data, cybersecurity, cloud, and IT modernization services.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years.
With $3.99 billion in revenue over the past 12 months, Everforth is one of the larger companies in the business services industry and benefits from a well-known brand that influences purchasing decisions. However, its scale is a double-edged sword because it’s harder to find incremental growth when you’ve penetrated most of the market. For Everforth to boost its revenue, it likely needs to adjust its prices, launch new offerings or expand into foreign markets.
Everforth struggled to increase demand as its $3.99 billion in revenue for the trailing 12 months was close to its revenue five years ago. This shows demand was soft.
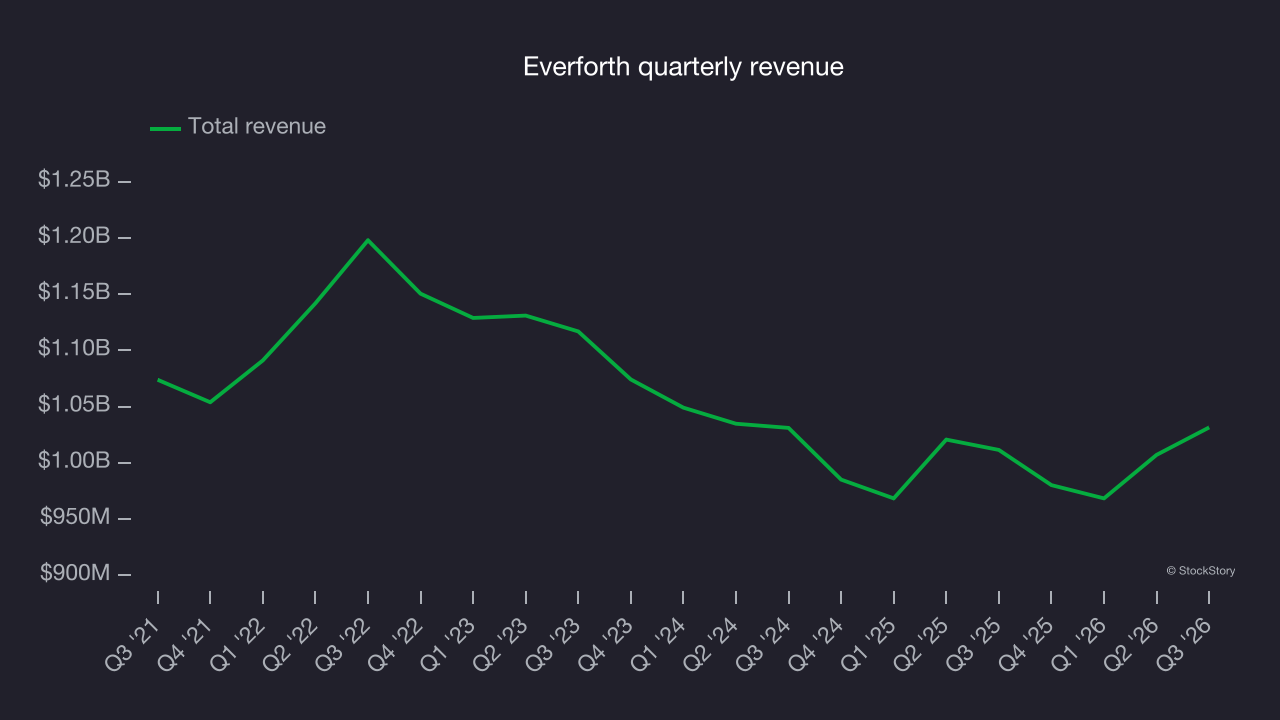
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. Everforth’s recent performance shows its demand remained suppressed as its revenue has declined by 2.4% annually over the last two years. 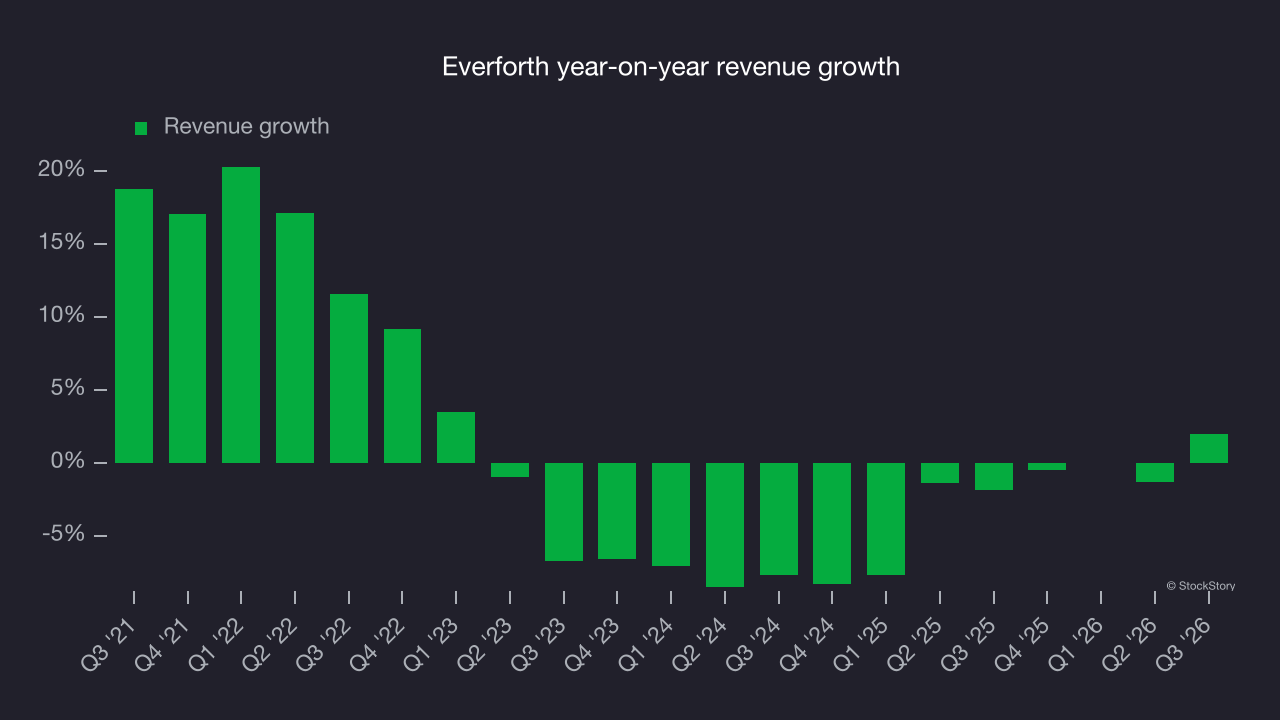
This quarter, Everforth reported modest year-on-year revenue growth of 2% but beat Wall Street’s consensus estimates by 2%. Company management is currently guiding for flat revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 1.1% over the next 12 months, according to S&P. While this projection indicates its newer products and services will spur better top-line performance, it is still below the sector average.
Adjusted operating margin
Adjusted operating margin is one of the best measures of profitability because it shows how much a company earns after subtracting all core expenses, like marketing and R&D. It also removes various one-time costs to paint a better picture of normalized profits.
Everforth was profitable over the last five years but held back by its large cost base. Its average adjusted operating margin of 9.4% was weak for a business services company.
Everforth’s adjusted operating margin decreased by 4.1 percentage points over the last five years. This poor performance shows that costs were rising and it couldn’t pass them on to its customers.
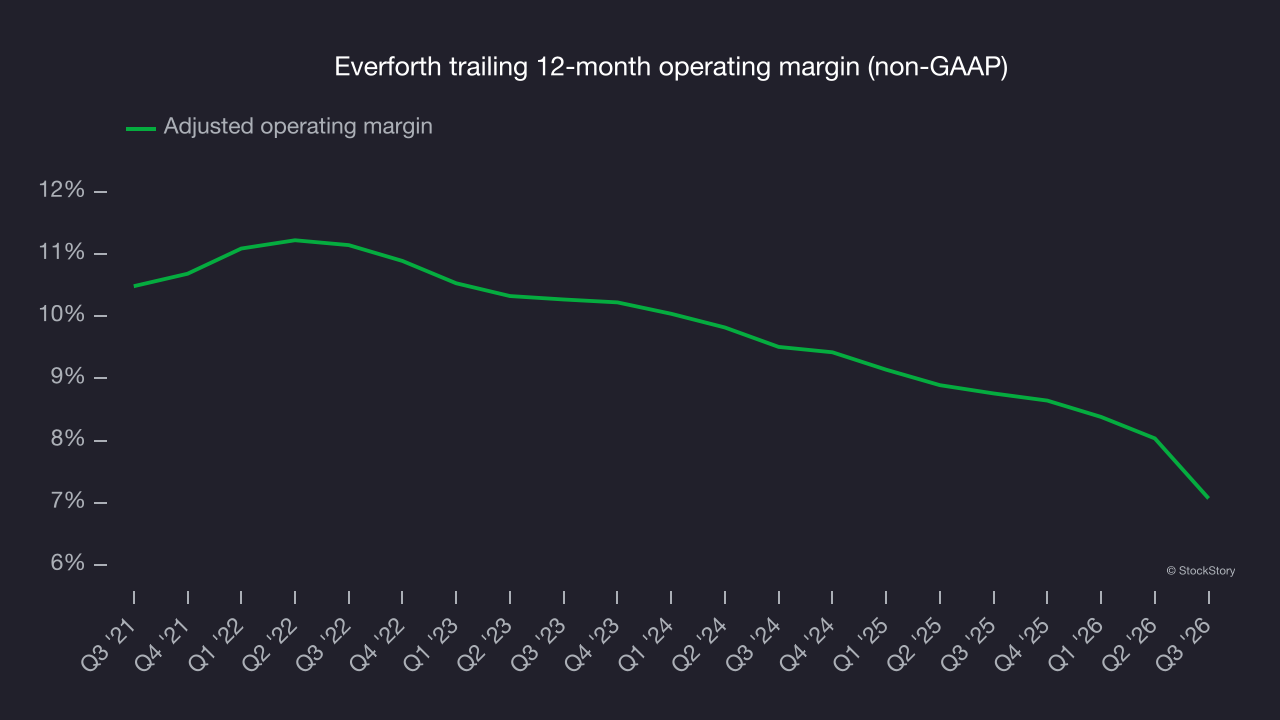
In Q3, Everforth generated an adjusted operating margin of 5.5%, down 3.8 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Everforth’s EPS declined by 6.4% annually over the last five years while its revenue was flat. The company struggled because its fixed cost base made it difficult to adjust to choppy demand.
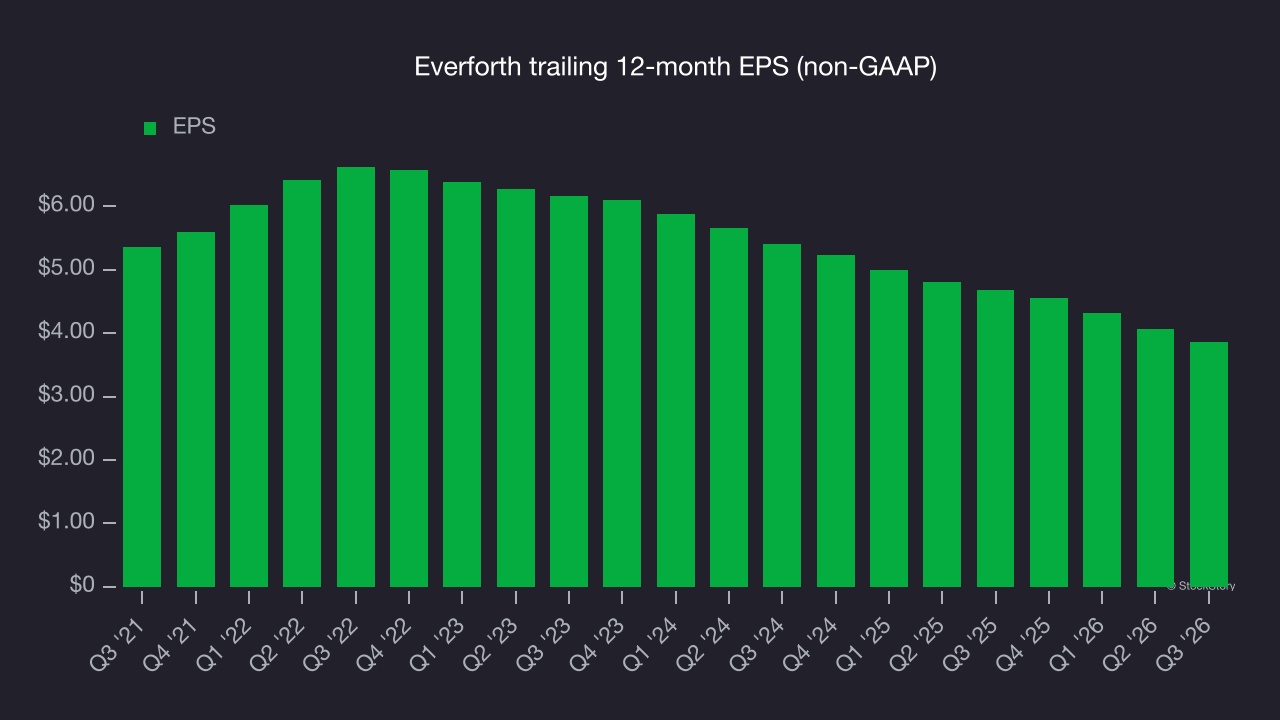
A closer look at Everforth’s earnings helps explain its performance. As mentioned earlier, Everforth’s adjusted operating margin declined by 4.1 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
As with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Everforth, its two-year annual EPS declines of 15.5% show it’s continued to underperform. The results were poor across both periods.
In Q3, Everforth reported adjusted EPS of $1.11, down from $1.31 in the same quarter last year. Despite falling year on year, EPS beat analysts’ consensus estimates by 6.6%. Over the next 12 months, Wall Street expects Everforth’s full-year EPS to grow 7.1% from $3.86 to $4.13, according to S&P.
Key takeaways from Everforth’s Q3 results
Everforth’s quarter had some key positives, with EPS and revenue both topping analysts’ consensus estimates. The outlook was less encouraging: revenue guidance for next quarter came in slightly below consensus. Shares rose 2.1% to $39.50 immediately after the results.
When evaluating Everforth, consider valuation, business quality and the latest earnings. Read the full research report for more (it’s free).